

Cash Advance - No credit Check
by D.J. Advance App
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 500.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
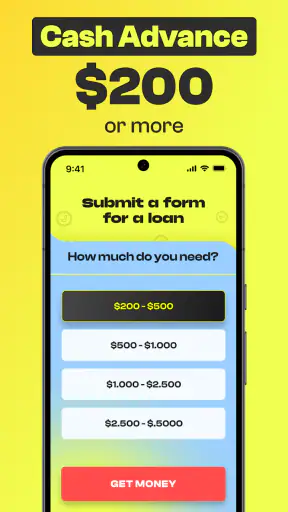
 Analysis by Getfullapps
When an unexpected bill lands before payday, the first thing I want from a finance app is clarity. Cash Advance - No credit Check is built around that urgent moment, presenting itself as a way to look for a cash advance without making the experience feel like a traditional loan application. I reviewed it with that use case in mind: not as a replacement for careful budgeting, but as a tool someone might open when timing matters and their regular income has not arrived yet.
The app comes from D.J. Advance App and is free to install. It belongs to the finance category, carries an Everyone age rating, and supports devices running Android 7.0 or later. Its current version is 1.1.3. Those details make it accessible to a wide range of Android users, including people with older phones, although accessibility should not be confused with guaranteed approval or guaranteed access to money.
What I found most important is the distinction between finding a possible cash advance and receiving funds. An app can simplify the first step, but the final result depends on the information requested, the provider involved, eligibility checks, and the terms shown during the process. I would use this app as an initial route to explore an urgent option, not as permission to borrow more than I can repay.
How the app feels when speed matters
The main appeal is its focus. Instead of opening a broad banking app and searching through savings, transfers, credit tools, and account settings, I can go directly to a cash-advance-oriented experience. That narrow purpose is useful when I am dealing with a short gap and need to understand what option may be available before payday.
Still, “instant” should be treated as an expectation about the application process rather than a promise that money will appear immediately. The app’s store summary emphasizes instant cash advances and no-credit-check loans, but responsible use means reading each screen carefully. A fast form is not automatically a fast payout, and “no credit check” does not mean there are no eligibility requirements or repayment consequences.
In everyday use, the best speed improvement comes from preparing before opening the app. I would have my income details, basic personal information, and repayment plan ready, while also checking that the phone has a stable connection. This avoids rushing through questions and then having to restart because an answer was incomplete or inconsistent.
A realistic example would be a utility bill due two days before a regular paycheck. I might open the app to see whether a suitable advance route exists, compare the amount I actually need with the repayment obligation, and stop if the terms do not fit my next pay cycle. That final step matters more than completing the application quickly. Borrowing extra simply because a larger amount appears available can turn a short delay into a longer financial problem.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
The app is also better suited to a focused, one-session check than to constant background use. I would not keep opening it repeatedly while waiting for an outcome. Instead, I would submit accurate information once, note any instructions or status messages, and give myself enough time to review the repayment details. If the need is truly urgent, I would also keep a backup plan, such as contacting the bill provider directly to ask about a payment arrangement.
What “no credit check” should mean in practice
The phrase can sound reassuring, especially to someone with a limited or damaged credit history. My advice is to read it narrowly. It may indicate that a conventional credit-score review is not the central part of the process, but it does not remove the need for identity information, income information, account checks, or other eligibility decisions. It certainly does not make borrowing cost-free.
Before accepting anything, I would look for the total repayment amount, any charges, the due date, and what happens if repayment is late. If those details are difficult to understand, that is a reason to pause rather than a reason to move faster. The app can help start the search, but I would never treat its short description as a substitute for the full terms presented during an application.
Handling heavy-use moments and practical workflows
Finance apps are rarely “heavy” in the same way as games or video editors. The demanding moment here is usually not graphics or processing power; it is the combination of form entry, network communication, account verification, and careful reading under pressure. Cash Advance - No credit Check is designed around that kind of task, so its value depends on keeping the process understandable when I am already worried about money.
One useful workflow is to separate eligibility checking from the final borrowing decision. I can first see whether the route appears relevant, then close the process and review my budget away from the urgency of the screen. I would write down my next payday, essential expenses, and the maximum repayment I can handle. Only after that would I return to decide whether continuing makes sense.
Another practical habit is to request only the amount tied to a specific need. If the immediate problem is a small grocery purchase or a bill shortfall, borrowing a larger amount creates unnecessary exposure. The app’s convenience may make a larger request feel easy, but convenience is exactly why I would set my own limit before beginning.
Heavy use can also mean switching between the app and other tools. I might check my banking app, calendar, email, or a bill statement while completing the process. On an older phone, moving between apps can cause a form to reload or lose unsaved information, so I would avoid filling everything out while multitasking. A calmer workflow is to gather the details first, use the finance app in one uninterrupted session, and capture important repayment information in a secure personal note.
Privacy deserves attention during this kind of multitasking. I would not enter sensitive financial information while connected to an unfamiliar public network, and I would avoid taking screenshots of personal details unless absolutely necessary. These are not special features of the app; they are sensible precautions whenever a financial application asks for personal information.
Where the experience may become frustrating
The biggest friction is likely to come from uncertainty rather than from the app’s basic purpose. A person may open it expecting a guaranteed advance, only to discover that an application still involves conditions or that the amount available does not match the amount needed. That gap between a short promotional summary and a real financial decision can be stressful.
I would also be cautious about repeated attempts. If an application does not work on the first try, submitting multiple versions with different information is a poor strategy. It can create confusion and make it harder to remember what was entered. A better approach is to check the information carefully, confirm that the device and connection are working, and seek support through the appropriate channel if the process remains unclear.
For people who need a detailed spending plan, automatic bill management, long-term savings tools, or a complete view of several accounts, this app is too narrow to be a full personal-finance solution. A conventional banking app or budgeting app will usually be better for monitoring cash flow over time. Cash Advance - No credit Check makes more sense as a focused option for exploring short-term access to cash.
Reliability, stability, and recovering from problems
The app has attracted a 4.7 average from around thirty-five thousand ratings, with roughly two thousand eight hundred written reviews, and it has passed half a million installs. That level of public use gives me some confidence that it is not an obscure experiment, but popularity does not guarantee that every application goes smoothly. Finance processes can fail for reasons outside the app itself, including connection problems, account mismatches, or eligibility decisions.
When I judge reliability here, I look for predictable behavior and clear recovery rather than expecting every request to succeed. If a page takes longer than expected, I would avoid pressing the submit button repeatedly. Duplicate actions are especially undesirable in a financial workflow. I would wait, check whether a confirmation appeared, and review any status screen before trying again.
If the app closes or the phone loses connection, I would reopen it and first look for an existing application status rather than immediately starting a new request. This is one of the most important recovery habits for a cash-advance tool: confirm what already happened before creating another action. I would also keep a record of the date and details of any submission, without storing sensitive credentials in an unsafe place.
Reliability also means knowing when to stop. If the repayment information is unclear, the requested access feels excessive, or the result does not arrive within the timeframe I can safely tolerate, I would move to a different solution instead of repeatedly refreshing. Calling the biller, asking an employer about payroll timing, or using an established bank facility may be slower but more predictable for some users.
The app’s free price is helpful for trying the initial experience without paying an installation charge. However, free access to an app does not mean that a financial advance is free. I would distinguish carefully between the app’s download cost and the cost of any borrowing option shown inside the process. That distinction should be part of the reliability check because unexpected charges can undermine an otherwise convenient workflow.
Stability on older Android devices
Support for Android 7.0 or later is a practical advantage for people who do not own a recent phone. It suggests that the app is not limited to the newest hardware, but older devices can still have less available memory, slower app switching, or outdated system components. I would close unused apps, keep enough storage free for normal operation, and update the phone where possible before beginning a financial request.
Resource demands are unlikely to be the central concern in a finance app with a form-based purpose. The more meaningful issue is whether the device can maintain a stable connection while moving through sensitive screens. A phone that handles ordinary browsing well may still struggle if its operating system, browser components, or security settings are heavily outdated.
I would also avoid using a modified operating system or an unsecured device for this type of task. Even when an app runs, the surrounding phone environment matters. Screen locks, current security updates, and careful handling of notifications reduce the chance that personal information is exposed to someone else using the device.
Who should use it, and who should choose another route?
I see the strongest fit for an adult who has a temporary timing problem, understands the amount needed, and can identify exactly how repayment will fit into the next income cycle. The Everyone rating makes the app broadly accessible in the store, but financial responsibility still requires adult judgment. Younger users should not interpret the age label as advice to borrow or as evidence that an advance is appropriate for them.
It may also suit someone who has difficulty qualifying for conventional credit and wants to explore an alternative route. Even then, I would compare the complete repayment obligation with other possibilities. A credit union, employer advance, existing overdraft facility, or direct payment arrangement may be more suitable depending on the person’s circumstances. The app is useful when it opens a realistic option, not when it encourages someone to stack one short-term advance on top of another.
I would skip it if I already know that my next paycheck is committed to rent, food, utilities, and other essential costs. In that situation, another repayment due soon could deepen the shortage. I would also avoid it if I need a large, long-term loan, want detailed credit-building support, or require a complete budget dashboard. Those needs call for a different kind of financial service.
Compared with a regular bank app, this tool appears more focused on the immediate cash-advance question and less suited to managing an entire financial life. Compared with a budgeting app, it addresses access to money rather than helping me plan spending over months. Compared with borrowing directly from a familiar provider, it may be a convenient starting point, but the usual alternative may offer terms or support that are easier for me to understand. The right choice depends on whether speed and access outweigh the value of an established relationship.
My checklist before submitting anything
I would approach the app with a short personal checklist:
- Write down the exact amount needed instead of choosing an amount impulsively.
- Confirm the next income date and reserve money for essential bills first.
- Read the total repayment, due date, and any applicable charges in full.
- Use accurate information and avoid repeated submissions if the screen seems slow.
- Save only the non-sensitive details needed to track the request.
- Stop if the terms are unclear or repayment would depend on another advance.
This checklist adds a layer of control that the app itself cannot provide. It turns a rushed financial decision into a comparison between a specific shortfall and a specific repayment obligation. In my experience, that is the difference between using a cash-advance app thoughtfully and treating it like an emergency button.
Final performance verdict
Cash Advance - No credit Check is a focused finance app for people investigating short-term cash access before payday. Its free entry point, broad Android compatibility, and concentrated purpose make it easy to consider when time is tight. The strong user rating and substantial install base also make it feel more established than an app with little public use.
My positive view comes with an important boundary: I would recommend it for exploring an option, not for assuming approval, instant delivery, or effortless repayment. The app’s speed is most valuable when paired with preparation, accurate information, and a clear budget. Its resource requirements should be manageable on supported phones, but older devices and unstable connections can still make financial forms frustrating, so I would use it in a calm, uninterrupted session.
The most useful feature of the experience is its narrow focus; the most serious limitation is that narrow focus. It may help address a short gap, but it will not replace budgeting, banking, or debt advice. I would recommend trying it only when the repayment plan is already clear before the application begins. If the terms fit that plan, the app can be a convenient starting point. If they do not, a bill extension, employer option, trusted bank service, or local financial adviser is likely the safer choice.
Pros
- Fast application process with minimal paperwork
- Useful for handling unexpected short-term expenses
- Clear repayment schedules before accepting an offer
- No traditional credit check may help some borrowers qualify
- Funds may be deposited quickly after approval
Cons
- Advance limits can be relatively small
- Service fees or subscription costs may apply
- Repayment is often required within a short period
- Eligibility and availability may vary by location
- Late repayment could lead to additional charges or financial stress
FAQs for Cash Advance - No credit Check
What is Cash Advance - No Credit Check, and how does it work?
Cash Advance - No Credit Check is designed to help users explore short-term borrowing options through a mobile application. After entering personal, employment, and financial details, the app may connect you with lenders or loan providers. Approval, loan amounts, interest rates, fees, and repayment terms are determined by the provider, not necessarily by the app itself. Read every offer carefully before accepting.
Can I really get a cash advance without a credit check?
The phrase “no credit check” should be interpreted carefully. Some providers may consider alternative information instead of relying only on a traditional credit score, while others may still perform a soft or hard credit inquiry. Approval is never guaranteed, and eligibility can depend on your income, banking history, location, employment, and other requirements. Review the provider’s privacy and lending disclosures before submitting an application.
How much does a cash advance cost, and what fees should I expect?
The total cost can vary significantly depending on the lender and the type of advance offered. Possible charges include interest, origination fees, service fees, late-payment penalties, expedited funding fees, or recurring membership costs. Some short-term loans can have a very high annual percentage rate. Before agreeing, compare the amount received with the total repayment amount and confirm whether any fee is charged even when you are not approved.
How quickly will the money arrive after I am approved?
Funding speed depends on the lender, your bank, the time of day, and whether you choose standard or expedited delivery. Some offers may provide funds on the same business day, while others can take one or more business days. The app may only facilitate the application and does not guarantee immediate deposits. Make sure your bank account information is accurate and check for any express-transfer fee.
Is Cash Advance - No Credit Check safe to use, and what information does it require?
Before using the app, review its privacy policy, permissions, developer information, and user feedback. Applications for cash advances commonly request identity, contact, income, employment, and bank-account details, so only provide information through a secure and trustworthy service. Avoid apps that promise guaranteed approval, request upfront payment through unusual methods, or pressure you to accept unclear terms. Borrow only what you can repay on time.











